Insights
DAIM Insight
Explore the latest trends in manufacturing and logistics innovation through expert insights.
Opening
A $25B Market Opens: Why Manufacturing Is Shifting Its Eyes to Logistics Robots
Estimated at $17B to $25B by 2035, with a near-20% CAGR, the Autonomous Mobile Robot (AMR) market is among the fastest-growing segments in manufacturing today. Factoring in overhead transport (OHT) and broader logistics automation, the total addressable market expands even further.
This rapid expansion signals more than high robot adoption; it reflects a strategic shift in enterprise investment from automating standalone machines to orchestrating factory-wide material flow.
How fast is this shift happening? In this issue, we examine global market data driving logistics automation and trace the key technological developments leading this transformation.
Key Highlights
The $25B Logistics Robot Market and the Rise of Central Orchestration
-
Key Highlight 01
Rapid expansion of the $25B AMR market and the strategic shift from standalone assets to factory-wide flow
-
Key Highlight 02
3D automation scaling across the entire plant floor—from ground AMRs to ceiling-mounted OHTs
-
Key Highlight 03
The rise of integrated fleet orchestration platforms, shifting the focus from robot headcounts to heterogeneous fleet control
Trend
DAIM Thoughts
Manufacturing Competitiveness Now Lies in the ‘Flow’
Market Growth in Logistics Robotics: What the Data Shows
Visit modern factories and distribution centers today, and the sheer proliferation of robotics is immediately noticeable. This is not merely an anecdotal observation—global market research data strongly corroborates the shift.
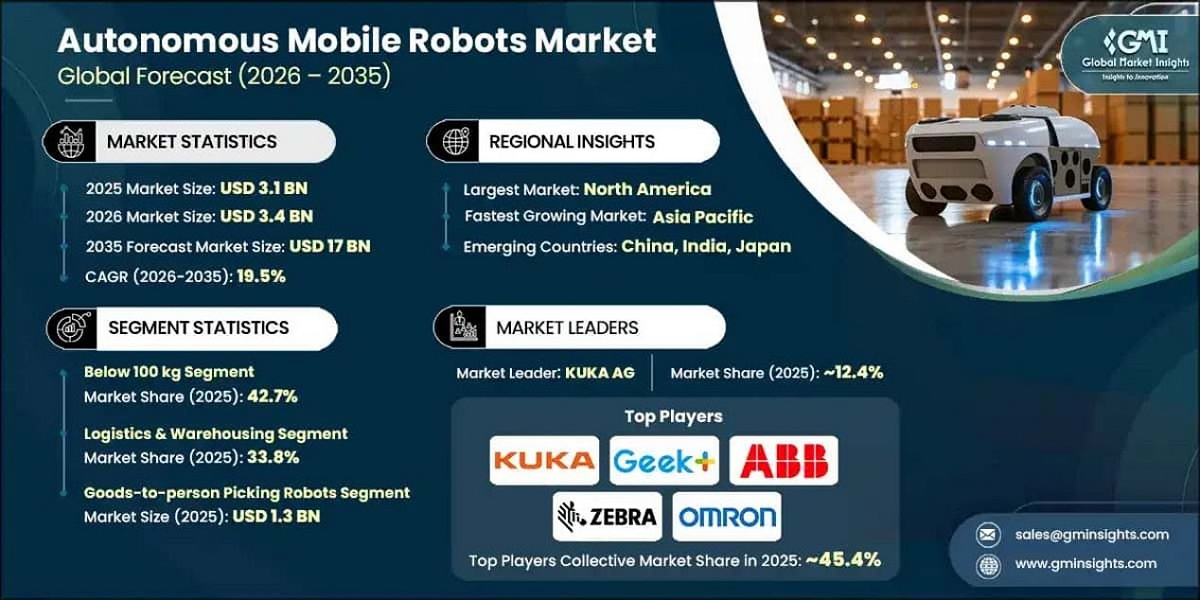
■ Global AGV/AMR Market Trajectory 1 (GMI Analysis)
Source: Global Market Insights, 「Autonomous Mobile Robots Market Forecast (2026–2035)」
According to the latest report from Global Market Insights (GMI), the global Autonomous Mobile Robot (AMR) market is projected to surge from $3.4 billion in 2026 to $17 billion by 2035. This represents an aggressive compound annual growth rate (CAGR) of 19.5%.
The primary growth drivers are well-defined. E-commerce expansion and warehouse automation lead the sector, accounting for 24% of demand, followed closely by initiatives to improve operational safety and efficiency across manufacturing and logistics facilities (19%). By optimizing workflows and safeguarding shop-floor operators, AI-driven AMRs are expanding rapidly from warehouse settings into broader industrial manufacturing plants.
The competitive landscape is equally notable. Market leader KUKA AG currently holds approximately 12.4% market share, competing alongside industry leaders such as Geekplus, ABB Robotics, Zebra Technologies, and Omron. The top tier commands a combined market share of roughly 45.4%, demonstrating a market led by high-tech engineering innovators.
By region, North America remains the largest overall market today. However, the Asia-Pacific region—driven by South Korea, China, India, and Japan—is recording the fastest growth, fueled by surging integration demand with next-generation smart factories.
Reinforcing this outlook, Business Research Insights similarly projects the AMR market to scale aggressively into a multi-billion-dollar industry in the coming years.

■ Global AGV/AMR Market Trajectory 2 (Business Research Insights Analysis)
Source: Business Research Insights, 「Global Autonomous Mobile Robot (AMR) Market Size」
• 2026 Market Size: $6.17 Billion
• 2035 Projected Size: $25.4 Billion
• Compound Annual Growth Rate (CAGR, 2026–2035): 17.02%
Logistics Robotics Expands Across Full 3D Facility Spaces
A compelling industry shift is the diversification of robotic form factors and their deployment across entire three-dimensional plant environments.
Until recently, material handling automation relied predominantly on Automated Guided Vehicles (AGVs) navigating fixed magnetic strips or optical markers. Today, AMRs equipped with LiDAR and advanced vision systems—capable of autonomous navigation and obstacle avoidance—are scaling rapidly.
Moreover, intralogistics automation is no longer confined to the floor. It is scaling into high-bay storage, ceiling space, and outdoor yards:
• AMRs (Autonomous Mobile Robots)
Flagship mobility platforms that autonomously navigate facility floors to transport parts and materials.
• Automated Forklifts
A specialized class of AMRs/AGVs automating pallet transport and high-rack stacking across manufacturing floors and logistics hubs.
• Shuttle AS/RS (Automated Storage and Retrieval Systems)
High-speed robotic shuttles moving vertically and horizontally within rack structures to automate inbound and outbound flows, maximizing storage density and throughput.
• OHT (Overhead Hoist Transport)
Ceiling-mounted rail vehicles engineered for cleanroom-sensitive manufacturing, such as semiconductor and display fabrication, to transfer wafers and delicate carriers.
• Automated Gantry Cranes
Autonomous overhead systems engineered for container handling and heavy payload transfers across expansive manufacturing yards and intermodal terminals.
Modern logistics automation has evolved far beyond deploying a few standalone robots on the shop floor. By unifying floors, warehouses, overhead infrastructure, and yards, manufacturing logistics is transitioning into a fully synchronized, three-dimensional material flow.
This shift is driven not only by labor shortages, rising operational costs, and supply chain volatility, but also by the imperative to establish the foundation for autonomous manufacturing. We are witnessing a massive paradigm shift where AI mobility orchestrates the entire physical volume of the industrial plant.
As Robot Fleets Multiply, ‘Orchestration’ Becomes the Decisive Factor
Managing one or two mobile robots is relatively straightforward. However, when dozens or hundreds operate concurrently within the same facility, the operational reality changes fundamentally.
Traffic paths must be dynamically deconflicted, task priorities updated in real time, and instant workarounds deployed when bottlenecks or machine failures occur. Ultimately, competitive advantage hinges less on procuring another high-spec robot and far more on how intelligently the entire fleet is orchestrated.
Consequently, alongside hardware adoption, the market for Robot Fleet Management Software is witnessing accelerated growth.

■ Global Robot Fleet Management Software Market Trajectory
Source: The Insight Partners, 「Robot Fleet Management Software Market」
• 2025 Market Size: $719.46 Million
• 2034 Projected Size: $2.18 Billion
• Compound Annual Growth Rate (CAGR, 2026–2034): 14.85%
According to a 2026 report by The Insight Partners, the global robot fleet management software market is projected to expand from $719.46 million in 2025 to $2.18 billion by 2034—nearly a threefold increase. This represents pure software value expanding at an annual rate of roughly 14.9%.
A key metric stands out: cumulative enterprise spending on robot fleet management solutions between 2026 and 2034 is projected to reach approximately $13.8 billion.
Moreover, facilities rarely implement standalone fleet software in isolation. Implementations increasingly bundle MES, WMS, digital twins, physics simulation engines, and specialized robot operating systems. As a result, the broader operational software ecosystem is scaling far beyond isolated point solutions, compounding market value.
The Insight Partners identifies three core drivers fueling this growth:
• Operational Efficiency Gains
Demand for real-time fleet optimization to maximize throughput and plant productivity.
• OPEX Reduction
Strategic investments to mitigate rising labor dependencies and curb recurring operational costs.
• Safety and Operational Reliability
Stringent requirements to guarantee accident-free workflows in mixed human-robot operating environments.
Manufacturing competitiveness is no longer defined by how many robots sit on the balance sheet. Instead, it is dictated by the ability to integrate heterogeneous machines into a unified system and orchestrate full-plant flow with peak efficiency.
Gartner’s recent formalization of Multiagent Orchestration (MAO) platforms as a standalone market category confirms this evolution: the real battleground in industrial automation has definitively shifted from hardware deployment to centralized, intelligent system orchestration.
As the Market Surges, Why Does the Shop Floor Grow More Complex?
As market projections confirm, logistics automation is expanding at breakneck speed. Enterprises are aggressively onboarding AGVs, AMRs, OHTs, and AS/RS to lay the groundwork for lights-out dark factories.
Yet an inevitable question arises:
With robot headcounts multiplying, are manufacturing facilities genuinely operating with proportionate intelligence and efficiency?
On-the-ground reality tells a different story. Deploying one or two units is manageable, but the moment dozens of heterogeneous robots and automated systems interface simultaneously, unforeseen friction points surface. Routing deadlocks emerge, bottlenecks compound, and paradoxically, higher automation levels often yield greater operational complexity.
Ultimately, the defining challenge of intralogistics automation is not how many robots a plant introduces, but how effectively this expanding, disparate fleet is orchestrated as a single, coherent system.
In our next issue, we move past projections to confront operational reality on the factory floor.
We will dissect the primary pain points enterprises encounter during logistics automation, examine why industry leaders are pivoting from "hardware quantity" to "intelligent orchestration," and chart the strategic roadmaps required to navigate the road ahead.
2026.09.09
DAIM Focus